Investment Property Loans



Investment Property Loans Specialists Helping Australians Grow Their Property Portfolio
If you’re thinking about investing in property, chances are you’re not just looking for a loan.
You’re looking for confidence.
Confidence that you’re making the right decision
Confidence that your loan won’t limit you later.
Confidence that you’re setting yourself up to grow your property portfolio, not just buy one property and hope for the best.
At FirstPoint Mortgage Brokers, we help Australians secure the right investment property loan so they can build wealth through property with clarity, structure, and a long-term strategy in place.
As experienced investment property mortgage brokers, we don’t focus on short-term approvals; we focus on helping you build a property portfolio that works for you over time.

Why Investment Property Loans Deserve a Different Approach
One of the biggest misconceptions we see is that an investment property loan is “basically the same” as a home loan.
It’s very different.
Investment lending comes with:
- Different interest rates
- Different serviceability rules
- Different risk assessments
- Different long-term consequences
A loan that looks fine today can quietly reduce your borrowing power tomorrow, especially if your goal is to grow your property portfolio.
That’s why working with an investment property mortgage broker who understands the bigger picture matters far more than simply getting approved.
What Is an Investment Property Loan?
An investment property loan is used to purchase a property that generates income or capital growth, rather than being your primary residence.
In Australia, these loans are assessed differently by lenders because:
- Rental income is treated conservatively
- Investors are seen as higher risk
- Portfolio size impacts future borrowing
This means the way your investment property loan is structured can directly affect:
- How many properties can you buy
- How quickly you can scale
- How much flexibility you retain
The goal isn’t just to buy a property, it’s to create a structure that allows you to keep moving forward.
Thinking About Building a Property Portfolio?
Most investors don’t start out thinking, “I want five properties.”
They start with:
- “I want a smart investment.”
- “I want passive income.”
- “I want to build long-term wealth.”
Over time, that turns into a property portfolio and that’s where planning becomes critical.
We regularly speak with investors who say:
- “I didn’t realise this loan would affect my next purchase.”
- “I wish I’d structured things properly from the start.”
- “I thought approval meant I was doing it right.”
At FirstPoint Mortgage Brokers, we help you avoid those conversations by designing lending strategies that support your future, not limit it.
How We Help You Grow Your Property Portfolio
Our role as your investment property mortgage broker is simple in theory, but powerful in practice.
We help you borrow with intention.
That means:
- Structuring loans with future purchases in mind
- Choosing lenders that support investors
- Protecting your borrowing capacity
- Avoiding common portfolio roadblocks
We don’t believe in one-size-fits-all solutions. Every investor’s situation is different, and your investment property loan should reflect that.
A More Human Approach to Investment Lending
You might be wondering:
- “How much can I actually borrow?”
- “Will this loan stop me from buying again?”
- “Am I doing this the right way?”
These aren’t just technical questions; they’re real concerns and they deserve real answers.
We take the time to understand:
- Your income and job stability
- Your risk comfort level
- Your long-term goals
- Where you want your property portfolio to be in the future
From there, we design a lending strategy that supports confidence, flexibility and growth.
Why Loan Structure Matters More Than Most People Realise
One of the most common mistakes property investors make is focusing only on the property, not the loan behind it.
Poor loan structure can:
- Reduce future borrowing power
- Create unnecessary risk
- Lock properties together
- Make refinancing difficult
We often work with clients who were “approved” by a lender, only to discover later that the structure made it harder to grow their property portfolio.
Our approach prioritises:
- Clean loan separation
- Strategic use of equity
- Flexibility for future purchases
Because getting approved isn’t the finish line, it’s just the beginning.
Using Equity to Expand Your Property Portfolio
Equity is one of the most powerful tools available to property investors, but only when used correctly.
As your properties grow in value, equity can help fund future investments. However, accessing equity without a clear strategy can increase risk and reduce flexibility.
As an experienced investment property mortgage broker, we help you:
- Access equity safely
- Preserve serviceability
- Maintain portfolio flexibility
- Plan your next purchase strategically
This approach enables you to grow your property portfolio in a sustainable and stress-free manner.
Choosing the Right Lender Matters More Than You Think
Not all lenders support investors equally.
Some lenders:
- Reduce borrowing capacity after one or two properties
- Penalise portfolio investors
- Restrict interest-only lending
- Are conservative with rental income
Others are far more investor-friendly.
At FirstPoint Mortgage Brokers, we compare options across a wide lender panel to match you with lenders that align with your investment strategy, not work against it.
This flexibility is one of the biggest advantages of working with an independent investment property mortgage broker.
Interest-Only vs Principal & Interest — What’s Right for You?
There’s no “one right answer” when it comes to repayments.
Interest-only loans may:
- Improve cash flow
- Support portfolio growth
- Assist with tax planning
Principal and interest loans may:
- Reduce debt faster
- Improve lender perception
- Suit lower-risk strategies
The right choice depends on your goals, income, and property portfolio strategy and we’ll walk you through the pros and cons in plain language, not banking jargon.
First-Time Property Investors: Start Strong
If this is your first investment property, what you do now matters more than you might think.
Your first investment property loan often becomes the foundation of your future portfolio, for better or worse.
We help first-time investors:
- Understand borrowing power
- Avoid common structuring mistakes
- Plan for future purchases
- Build confidence from day one
Starting with the right advice can make the difference between buying one property or building a portfolio.
Experienced Investors and Portfolio Lending
As your property portfolio grows, lending becomes more complex.
Banks assess portfolio investors differently, and small policy changes can have big impacts on borrowing capacity.
We regularly work with:
- Investors with multiple properties
- Self-employed clients
- Trust and company structures
- High-income professionals
Our job is to help you adapt, restructure when needed and keep your momentum moving forward.
Supporting Your Broader Wealth Strategy
While we don’t provide tax or financial advice, we understand how lending fits into the bigger picture.
We regularly collaborate with:
- Accountants
- Financial advisers
- Buyer’s agents
This ensures your investment property loan complements your broader strategy and supports long-term property portfolio growth.
Why Choose FirstPoint Mortgage Brokers?
Choosing an investment property mortgage broker isn’t just about rates; it’s about guidance, experience and trust.
At FirstPoint Mortgage Brokers, we offer:
- Specialist investment lending expertise
- Portfolio-focused strategies
- Access to a wide range of lenders
- Clear, honest advice
- Ongoing support as your portfolio grows
We’re here for the long haul, not just the settlement date.
Our Simple, Supportive Process
We keep things straightforward:
1. Strategy conversation
We talk about your goals and where you want to go.
2. Borrowing assessment
We look at what’s possible now and in the future.
3. Loan structuring & lender selection
We design a solution that supports portfolio growth.
4. Application & settlement
We manage the process from start to finish.
5. Ongoing reviews
As your portfolio grows, we adjust your strategy.
Let’s Talk About Your Property Goals
Building a property portfolio isn’t just about numbers; it’s about confidence.
Confidence that your loan is structured properly.
Confidence that you’re not limiting your future.
Confidence that someone is looking at the bigger picture.
If you’re ready to explore the right investment property loan for your situation, we’d love to help.
Book a free, no-obligation chat with an investment property mortgage broker. Let’s talk about how you can grow your property portfolio with clarity and confidence.
Frequently Asked Questions
Knowledgeable. Trusted. Invested.
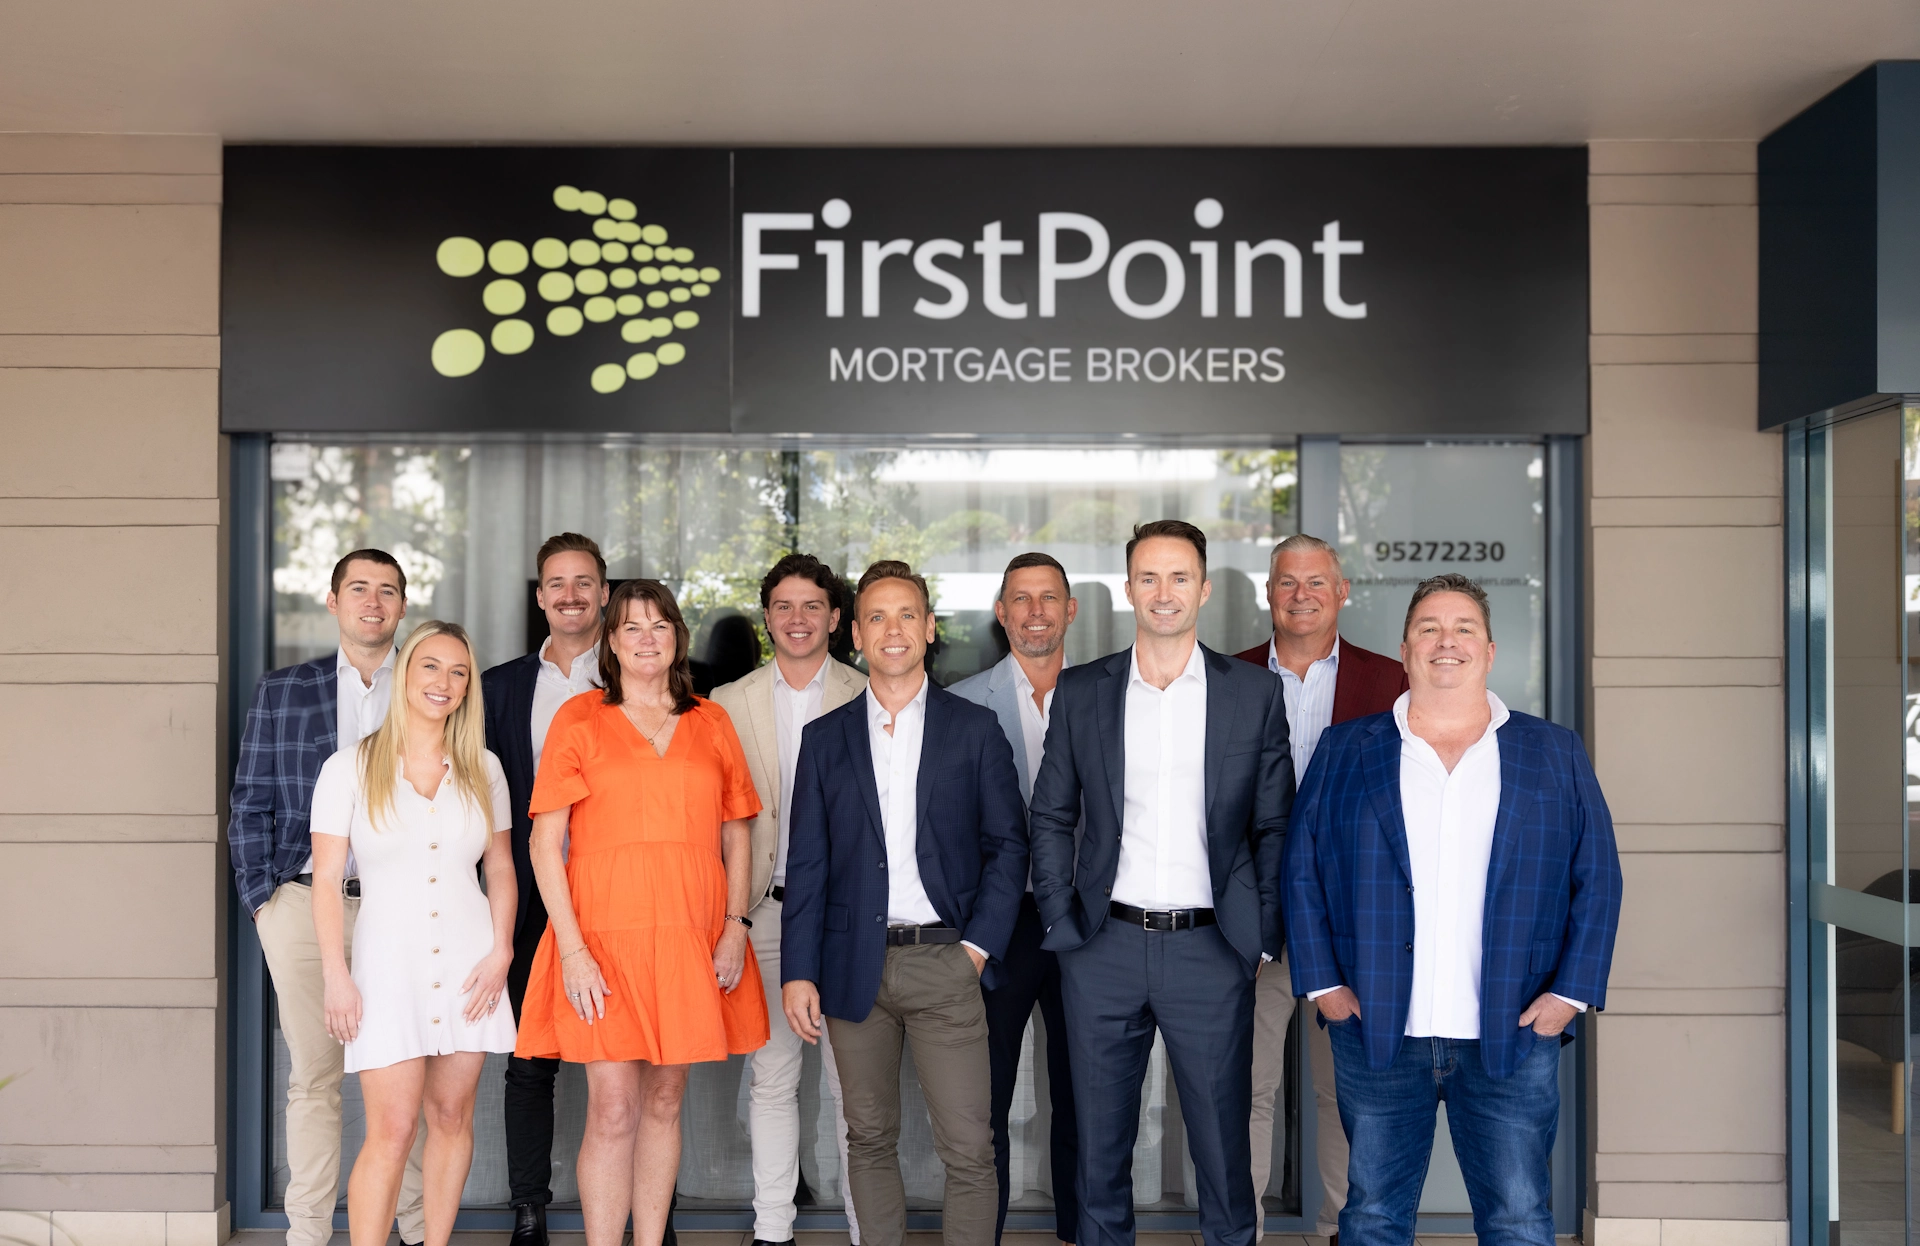
The award winning team at FirstPoint Mortgage Brokers in Cronulla are experts at assisting investors with their finance needs. The team can assist with:
- Loan structuring
- Fast pre-approvals (cases of loans approved within 24 hours)
- Very competitive interest rates
- P&I and interest only options
- High LVR loans
- Accessing equity to assist with purchasing an investment property
- Borrowing capacity scenarios when looking to build out a property portfolio
- Individual borrowers, Company borrowers and Trust borrowers
- Offset facilities and redraw capability
- Debt recycling
- LMI waivers for eligible professionals
Yes Jonathan Harris at FirstPoint Mortgage Brokers in Cronulla is an expert at assisting borrowers with their investment property loans. The team at FirstPoint Mortgage Brokers have 950+ 5 star reviews and can assist borrowers Australia wide. The team are renown for structuring investment loans at very competitive rates with fast turnaround times and a streamlined application process. For a stress free investment property loan application contact the team on 02 9527 2230.
The best way to secure your next investment property is to contact a mortgage broker for a review of your current financial position and potential borrowing capacity. A mortgage broker will assist with valuations on any existing property, potential equity that can be used toward the next purchase and will run various borrowing capacity scenarios based on your financial position across multiple lenders. A mortgage broker will complete a preliminary assessment based on your financial position and provide options you may qualify for regarding deposit amount required, borrowing potential, proposed repayments, P&I vs Interest only repayments, features like offset accounts etc.
Additionally, a mortgage broker will process the application from submission and navigating all steps through to settlement. Contact the team at FirstPoint Mortgage Brokers in Cronulla, you won’t be disappointed!
You may not always get the best home loan and investment loan rates from the same bank. It pays to shop around and is very common for borrowers to have several loans with various lenders. The reason for this is lenders all have a different appetite when it comes to home loans and investment loans, the pricing can vary substantially across lenders. Some of these variances in your application will determine the final product price and fees, these variances includes:
-LVR
- Loan size
- P&I or Interest Only
- Basic product or Package/Offset product
Speak to Chris Pryer, Greg Collins, Jonathan Harris or Chris Pryer from FirstPoint Mortgage Brokers who can complete a product comparison for both your home loan and investment loans. You may find the best deals could be split across multiple lenders, this something a mortgage broker can navigate and process on your behalf.
In a lot of cases yes another lender may be able to assist with additional lending if you have reached your borrowing capacity at your bank. The reason for this is the lenders have different credit policies ranging from different servicing stress test buffers to how they apply various types of income. A couple of examples of this:
Self Employed income – varying policies:
- Some lenders will average the last 2 years income
- Some lenders will use the last 1 year income in isolation
- Some lenders will expense business debts in serviceability
- Some lenders will exclude business debts in serviceability
Bonus income – varying policies:
- Some lenders will use the most recent years bonus income in isolation
- Some lenders will average the last 2 years bonus income
- Some lenders will use the lower of the last 2 years bonus income
As you can see above, the same income being received however treated very differently across multiple lenders. This will have a tangible effect on borrowing capacity.
These varying policies often result in large variances between lenders when it comes to borrowing capacity. A mortgage broker with access to a large range of lenders will be able to assist with reviewing and navigating the different credit policies to achieve the desired loan amount. The team at FirstPoint Mortgage Brokers have an in depth knowledge of lenders credit policies with over 20 years experience accessing both full doc and low doc loan options. Call FirstPoint Mortgage Brokers on 02 9527 2230
Yes a mortgage broker can assist with restructuring your loans before buying another investment property. A good idea to review your current interest rates, loan structure and product type (P&I or Interest only) when looking to acquire additional properties. A mortgage broker will compare hundreds of loans across multiple lenders to assist with setting up the right debt structures for your needs. A mortgage broker will assist with your application from the loan comparison stage, to loan submission all the way through to settlement.
Don't Just Take It From Us, Our Customers Are Our Biggest and Best Advocates


Jordan Toft
5 days ago
Expert knowledge, continuous availability, no question unanswered and executed precisely . From the get go Jonathan from FirstPoint Morgage Brokers delivered expert knowledge, specific to my situation, sourcing a unique product that encompassed my needs. Communication was direct and forthcoming with no situation or option left in ambiguity. No question was too small or insignificant and I was guided positively throughout the entire process linking all parties efficiently and effectively.
Securing finance, the right finance, is a key component in a process with many moving parts, having an informative, reliable and effective partner for this segment of the process was a great reassurance.
Response from the owner:Thanks Jordan, we really appreciate the fantastic feedback. Jono takes great pride in finding the right solution for each client, particularly when things aren't always straightforward. Great to hear his knowledge, communication and attention to detail gave you confidence throughout the process. Thanks again for trusting Jono and FirstPoint, and for taking the time to share your experience. Jordan so good to have you back in the FP fold.

Adam Deering
6 days ago
Chris was incredibly helpful and efficient, I would highly recommend.
Response from the owner:Adam, great 5 Star Review on Chris, thanks so much for choosing FirstPoint as your preferred Mortgage Broker, you know where to find us should you need us.

Rosanna Arrowsmith
7 days ago
Answered all our questions as first home buyers with no clue what we were doing. . Emails replied quickly, excellent communication and leads to conveyancer, a smooth and seamless process with the bank and the vendor. Extremely professional. We chose First Point Mortgage Brokers based on their 5 star rating and have zero regrets. Jonathan and the team highly recommended! Would give 6 stars if I could.
Response from the owner:Thanks so much, Rosanna, we’ll happily take the 6 stars! It’s great to hear Jono and the team made your first home buying experience feel smooth, clear and seamless from start to finish. Buying your first home is a huge milestone, so congratulations and thanks for putting your trust in FirstPoint based on our reviews. Now you’ve added another great one!

Emma and Liam
2 weeks ago
Absolute legend and the broker you want in your corner! We couldn’t have asked for a better broker than Chris while buying our first home. He was incredibly helpful, patient and easy to talk to throughout the whole process. He explained everything clearly, kept us updated and was always happy to answer our questions, no matter how small. Buying a home can feel overwhelming, but Chris made us feel supported and confident every step of the way. We’re so grateful for everything he did for us and would happily recommend him!
Response from the owner:Thanks Emma and Liam, what a fantastic review! Chris will absolutely love the “legend and the broker you want in your corner” call, can'y help but agree. Buying your first home is a huge milestone, so it’s great to hear he made the whole journey feel clear, supported and that little bit less daunting. Huge congratulations to you both, and thanks for trusting Chris and FirstPoint to help get you there.

Karen Yu
2 weeks ago
Excellent service. Easy to apply . Chris is very professional and keep me updated all the time. Great to deal with
Response from the owner:Thanks Karen, really appreciate the great feedback. Fantastic to hear Chris made the whole process easy and kept you informed every step of the way. Thanks again for trusting Chris and FirstPoint!

Belinda PARATHYRAS
2 weeks ago
Chris has been great in all aspects of our requirements.
Would highly recommend and will use again.
Response from the owner:Thanks Belinda, really appreciate the great feedback. Fantastic to hear Chris looked after you so well across the board. Thanks for the recommendation and your trust in FirstPoint, we look forward to helping you again down the track. You know where we are when you need to find us.

taysha whiteman
3 weeks ago
Response from the owner:Taysha, thanks for the 5-Star Review, that is all we strive for, spot on! Thanks.

Hayden Garn
3 weeks ago
These guys are first class!
Response from the owner:Thanks Hayden, you're a ledge, longtime client and great supporter, that is all we can ask for, you know where we are when you need us H.

Ben Counsel
3 weeks ago
Chris and the team at First Point and the best in the business. We have been dealing with them for many years now and have always been extremely happy with the outcome. Have recommended to friends and family with complete trust and confidence. Chris Pryer is an absolute gentleman and ultimate professional. Thanks for all your support.
Response from the owner:Ben, what a lovely review, thank you. It was great to have you and the family back again, so happy and excited to assist you guys with the new home. Ben, on behalf of Chris and the FP team thanks for the stamp of approval yet again. You know where we are if you need anything.

Naomi Russo
4 weeks ago
Jono has helped us with two properties and he has been wonderful both times. Would definitely recommend his services!
Response from the owner:Thanks Naomi, really appreciate the great feedback. Jono will love hearing it. Repeat clients and recommendations like this mean the world to us. Thanks again for the continued trust.